Wait, I got off on a bit of a rant there. This piece isn’t about photo credit, it’s about credit, as in, I will loan you money if you pay me back more than I gave you. THAT kind of credit.
On a loan of $125,000, according to our friends at Freddie Mac, a 7% interest rate for good girls and boys means you pay a monthy combined total for principal and interest of $831.63. Bad girls and bad boys, you have a 12% interest rate, and pay $1,285.77. That means you’re paying $454.14 and a total of an additional $163,490 over the life of the 30 year mortgage. Man, that sucks!
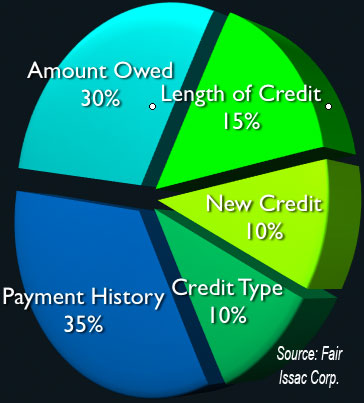 So, just how do these sharks calculate what your percentage rate is? Well, the higher the risk you won’t pay them back, the higher the interest rate. The folks at Fair Issac Corporation (FICO) are in charge of your future.
So, what is your credit score? If the end result of between 500~579, you suck. You’ve not paid your bills on time. You, sir or madam, are a bad credit risk. If you’re in the 760~850 range, you’re golden. A perfect risk. To find out, our dear friends in the federal government have deemed it necessary for you to get one free credit report, every year. How? check out www.AnnualCreditReport.com to learn more. There are three credit bureaus that have got your number, they are Equifax, Experian, and TransUnion.
Once you’ve got your number, here are a few suggestions:
- You need to have credit cards. Creditors don’t like people who keep cash in their mattress, they like you to play in their sandbox awhile with other people’s money before they will loan you theirs at a good rate.
- Don’t max out your cards. Get two, and rack them up only half way. They like this better than maxing out.
- Have a good mix. Those student loans, a car loan, and a few credit cards look better to them.
- A big paycheck doesn’t mean a good credit rating.
- Be a timely bill payer. Set up your cards to be paid automatically from your bank account so you don’t forget.
If you have been a bad boy or girl in the past, but are on the straight and narrow now, potential new creditors like that. More weight is given to recent credit entries in your history with the bureaus than older bad listings. Bills such as your cell phone bill can also affect your credit rating if you pay it late, and if you try to open a line of credit at a camera store, a bad credit score will preclude that.
Once you’ve paid your bills on time, and have good credit, then go on and worry about the point size of your photo credit, and whether or not the magazine will print your photo credit as your URL instead. (and have you tried that?)
Please post your comments by clicking the link below. If you’ve got questions, please pose them in our Photo Business Forum Flickr Group Discussion Threads.
Originally published on Photo Business News & Forum on May 8, 2007. Comments are closed; this post is part of the archive.
I do disagree with you on the credit card issue. I understand that you are writing on how to improve your FICO score and that is a way of doing it if done correctly. The problem is that line of thinking is the gateway drug for too many people to get into TOO much trouble. Not all mortgage loans are based only on your FICO score. You can still find people who will manually underwrite your loan and look at you as an individual.
I have seen too many photographers get into credit card debt early and just stay that way. There is a pervasive culture among us to think that we don’t make much and have to live that way. I disagree.
Cash is still king and when you budget correctly, everything from cameras to cars can be purchased with it and nothing else. So for the poster “Credit Card Holder”, don’t do anything foolish with your credit card.
For a great book on debunking the myths of living on the FICO score and credit, pick up “The Total Money Makeover” by Dave Ramsey. It is an eye opener for all of us who have grown up nurtured by Visa, Master Card and American Excess.
I registered my business as an LLC and I keep business and personal accounts at my bank. The large sums via the credit cards still count toward my credit score (which is in the 700’s) and I am paying off a business loan for a medium format digital back, all of which raises my score. Automatic payments on the loan.
Besides John’s excellent book, APA National (http://www.apanational.com) has some excellent papers you can download from their site that can help you with your business.
Strongly suggest to all that they attend any of the APA business seminars.
Keeping your act together with billing software is a good way to go. Some people use Quickbooks for everything, others use Quickbooks for the second half of the process.
The two gold standards for ease of use and up-to-date invoicing programs for photographers are: BlinkBid (http://www.blinkbid.com) and FotoBiz (http://www.fotobiz.net).
They are both excellent programs. I switched after many years of anquish from InView/Stock view to BlinkBid and love the program. Written by a working Los Angeles shooter, it is well thought-out and clearly presented.
Hope this helps.
Great topic by the way.
To me, it has a cyclical racketeering feel to it. I am not a conspiracy theorist by any stretch of the imagination, but having the credit world dictate that the best way to get a good rating with THEM is to borrow more money, well….I think there were some legbreakers back in Jersey that had a similar business plan.
Now, the idea of getting a card, buying a new supercomputer and paying it off over the subsequent months is a VERY attractive prospect….perhaps that is why credit cards are not a good idea for me. 😉
Thus, avail bad credit personal mortgages and overcome all financial hurdles being faced due to bad credit history.
asus s5000a battery
asus s5a battery